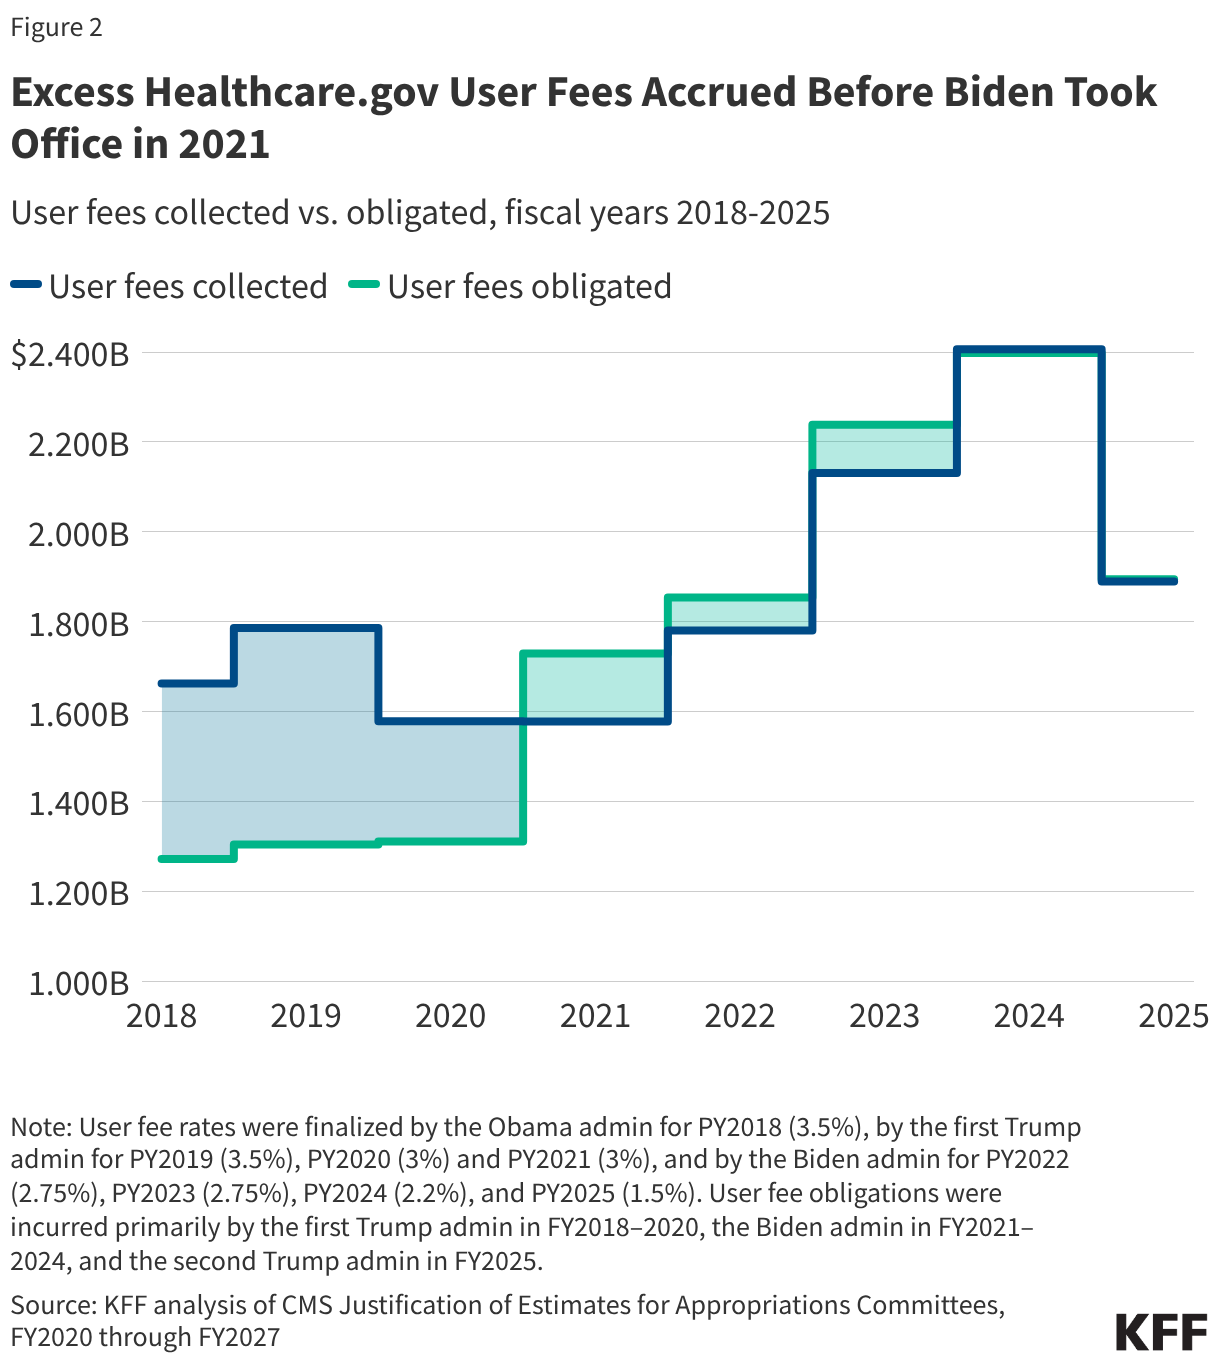
In September 2026, the Trump administration introduced a novel and controversial fiscal maneuver within the healthcare sector: the "Working Families Obamacare Refunds." President Trump announced that the federal government would issue one-time $500 checks to approximately one million Americans across 30 states. The administration framed these payments as a return of "excess user fees" collected by HealthCare.gov during the Biden presidency.
n
However, a deep dive into the mechanics of the Affordable Care Act (ACA) Marketplace, the history of federal user fees, and the current trajectory of insurance premiums suggests that this $500 payout is both a legal anomaly and a fraction of the cost increases currently being absorbed by the very families receiving the checks. While the administration presents the move as a corrective measure for bureaucratic over-collection, policy analysts and healthcare economists view it as a selective redistribution that ignores the broader financial pressures facing Marketplace enrollees.
n
Main Facts: The Scope and Eligibility of the $500 Checks
n
The "Working Families Obamacare Refunds" are not a universal benefit. According to the White House fact sheet and data from the Department of Health and Human Services (HHS), the checks are targeted at a specific and relatively small slice of the insurance-buying public.
n
Targeted Demographics
n
The payments are reserved for individuals who enrolled in health plans through the federal HealthCare.gov platform for the 2026 plan year and did not receive any premium tax credits (subsidies). This group represents roughly 5% of all ACA Marketplace enrollees. The remaining 95%—those who receive subsidies or who are enrolled through state-based exchanges like those in California or New York—will receive nothing. Furthermore, individuals who were enrolled in previous years but dropped their coverage prior to 2026 are excluded, despite having contributed to the user fee surplus the administration claims to be "refunding."
n
Geographic Limitations
n
The checks will only reach residents in the 30 states that utilize the federal HealthCare.gov platform. States that operate their own independent exchanges (State-Based Marketplaces or SBMs) manage their own fee structures and operations; consequently, their residents are ineligible for this federal "refund," even if they are unsubsidized.
n
Financial Discrepancy
n
The administration has characterized the $500 as a flat refund. However, HHS data reveals that the average user fee paid by an unsubsidized enrollee in 2026 is approximately $221. This indicates that for many recipients, the check exceeds the actual fees they paid into the system this year, while for others—particularly older enrollees with high-cost premiums—the $500 represents only a small portion of their total contribution to marketplace operations over time.
n
Chronology: The Evolution of Marketplace User Fees (2014–2027)
n
To understand where this "surplus" originated, one must trace the history of the FFM (Federally Facilitated Marketplace) user fee, which is a percentage of the monthly premium built into the cost of every plan.
n
The Obama and First Trump Terms (2014–2021)
n
From the inception of the ACA Marketplaces in 2014 through 2019, the FFM user fee remained steady at 3.5% of the total premium. In 2020, the first Trump administration lowered the fee to 3.0%, citing "operational efficiencies." Just before leaving office in January 2021, the Trump administration proposed a further reduction to 2.25% for the 2022 plan year.
n
The Biden Administration Adjustments (2021–2025)
n
Upon taking office, the Biden administration revised the 2022 fee upward to 2.75% to account for increased contract costs and a renewed focus on consumer outreach. However, as enrollment surged due to the "enhanced premium tax credits" introduced by the American Rescue Plan and the Inflation Reduction Act, the Biden administration was able to lower the fee percentage while still collecting significant revenue. By 2025, the user fee reached an all-time low of 1.5%.
n
The Transition and Second Trump Term (2025–2027)
n
In early 2025, as the Biden administration prepared to exit, it set a bifurcated rate for 2026: 2.2% if subsidies were extended, and 2.5% if they were not. Because the enhanced subsidies were allowed to expire, the rate defaulted to 2.5%. Upon returning to power, the second Trump administration proposed maintaining the 2.5% rate but ultimately finalized a 1.9% rate for the 2027 plan year. The $500 checks announced in September 2026 are ostensibly drawn from the surplus revenue generated during these fluctuating periods.
n
Supporting Data: User Fee Accumulation vs. Consumer Spending
n
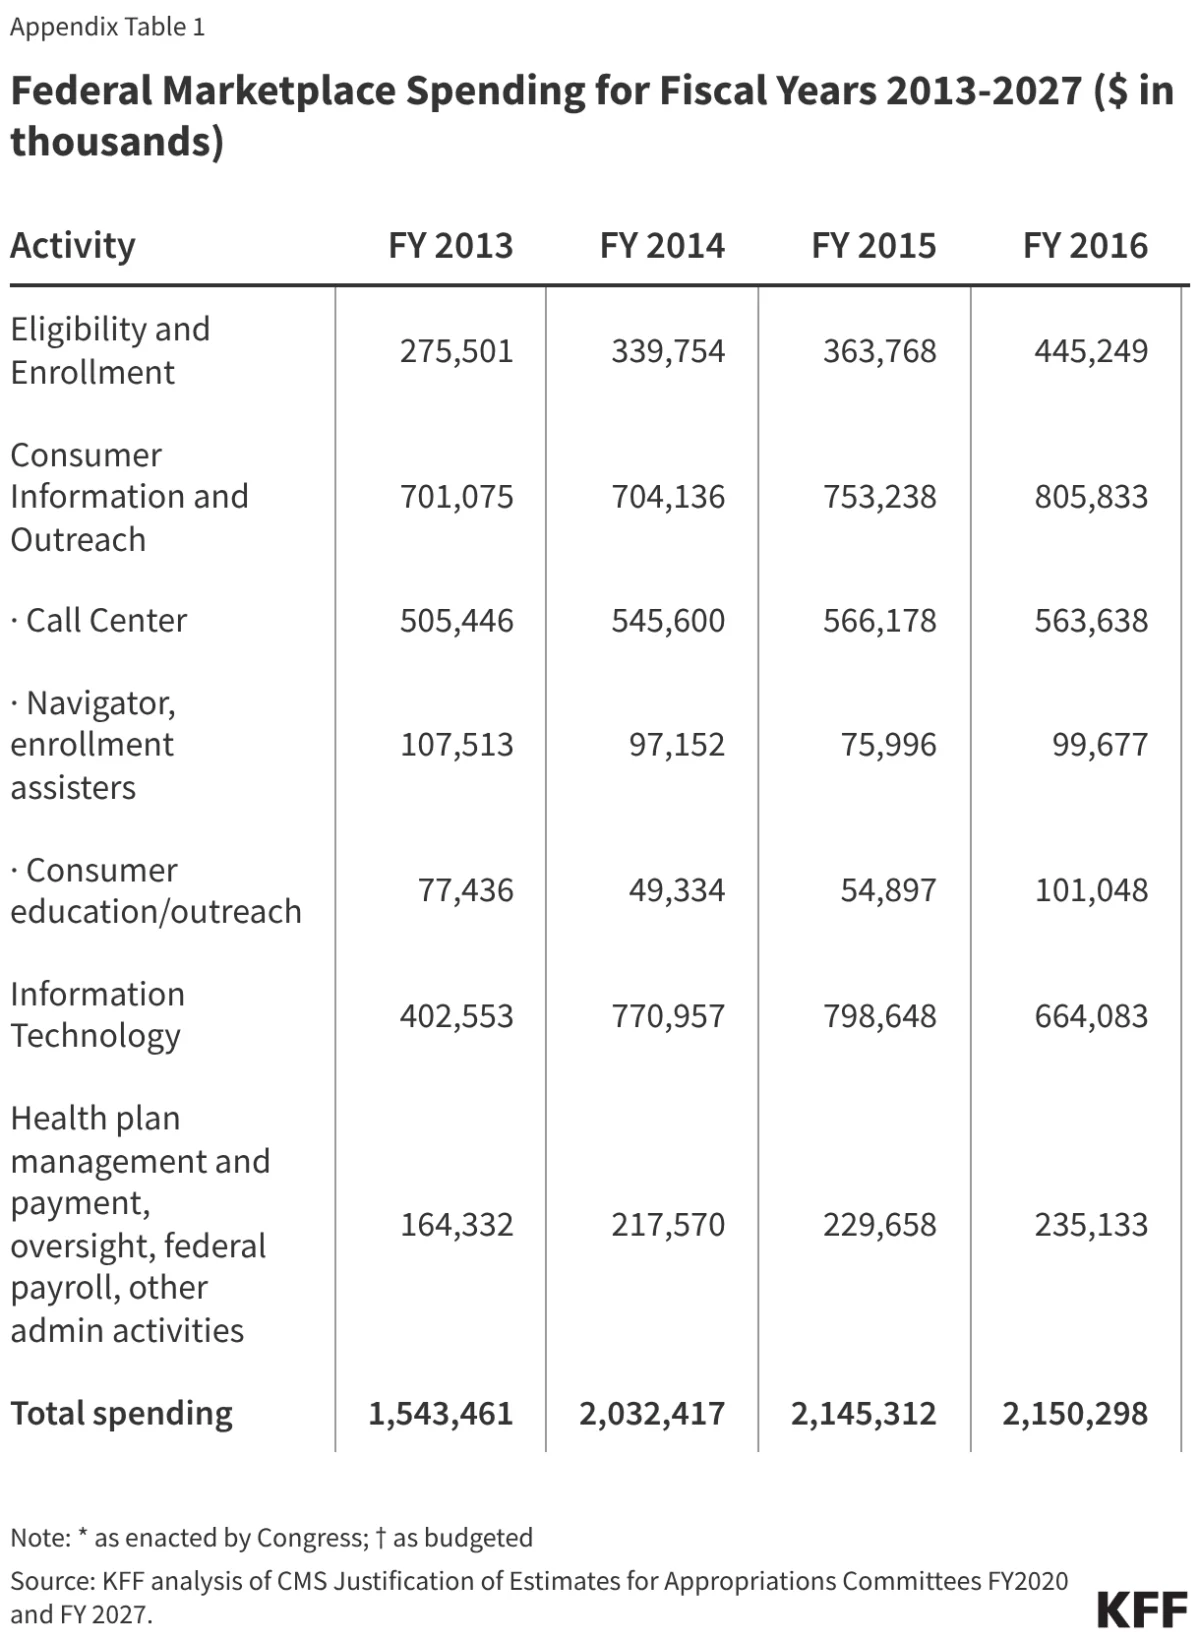
The central tension of the $500 refund lies in the math. The administration claims to be returning over-collected funds, but a review of CMS "Justification of Estimates" documents shows that the "surplus" is as much a result of spending cuts as it is of fee collection.
n
Spending on Outreach and Navigators
n
A significant portion of the user fee revenue is traditionally used for "Consumer Information and Outreach." During the first Trump term, spending on Navigators (personnel who help people sign up for coverage) was slashed from $100 million in 2016 to $20 million in 2020. The Biden administration reversed this, spending $1.2 billion on outreach by 2023. The second Trump administration has again moved to reduce these expenditures, with 2027 budget projections showing continued cuts. By spending less on helping people enroll, the administration creates a larger "surplus" in the user fee account.
n
The Premium vs. Refund Gap
n
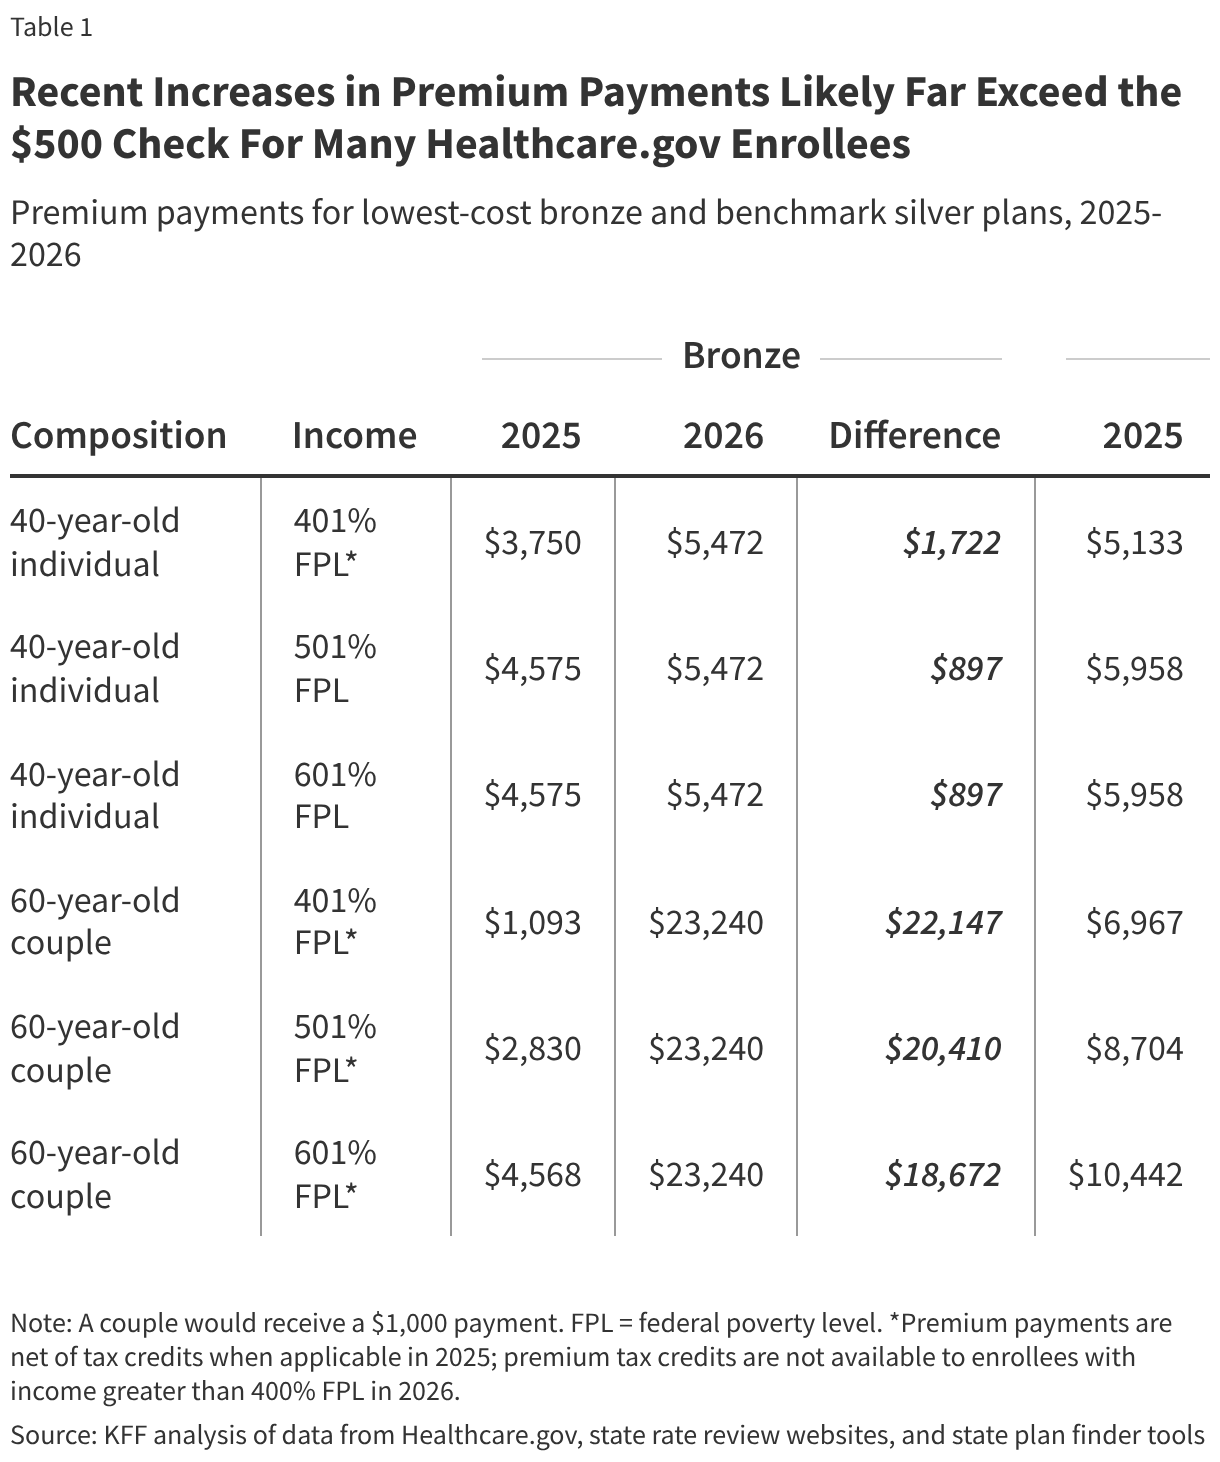
The $500 check arrives at a time when unsubsidized premiums are skyrocketing. With the expiration of enhanced tax credits, the average annual premium for an unsubsidized HealthCare.gov enrollee rose from $6,660 in 2025 to $8,844 in 2026—a $2,184 increase.
n
| Demographic Profile | 2025 Premium (Subsidized) | 2026 Premium (Unsubsidized) | Total Increase | Refund Impact |
|---|---|---|---|---|
| 40-year-old (401% FPL) | $3,750 | $5,472 | $1,722 | Offsets 29% |
| 60-year-old Couple (401% FPL) | $1,093 | $23,240 | $22,147 | Offsets 4% |
For a 60-year-old couple, the $1,000 they might receive (two $500 checks) is a negligible drop in the bucket compared to a $22,000 premium hike.
Official Responses and Legal Ambiguity
The announcement of the checks has been met with significant skepticism regarding the legal authority of the executive branch to issue such payments.
Lack of Precedent
Historically, the federal government has never returned unused user fees directly to consumers. In previous administrations, surpluses were simply "carried over" to future fiscal years to keep future fee rates lower or to fund marketplace IT upgrades. The ACA statute allows Marketplaces to charge fees to "fund operations," but it does not explicitly grant the HHS Secretary the power to cut checks to individual citizens from those fee accounts.
The Administration’s Stance
The White House maintains that the checks are a necessary "refund" for "Biden-era over-collection." Administration officials argue that since the fees were built into premiums paid by consumers, the consumers are the rightful owners of the surplus. They have characterized the move as a "Working Families" initiative, though critics point out that the recipients are, by definition, the highest-income earners on the exchange (those earning above 400% of the federal poverty level).
Legal Challenges
Legal experts have suggested that the "refunds" could be subject to litigation. Because the user fees were paid to the government by insurance issuers (who then passed the cost to consumers), some argue that if a refund were to happen, it should technically go back to the insurers or be used to reduce the federal deficit. There is also the question of whether this constitutes an unauthorized appropriation of federal funds, as Congress typically holds the "power of the purse."
Implications: The Future of the Marketplace
The decision to issue $500 checks rather than reinvesting the funds into the Marketplace or lowering future premiums has several long-term implications.
1. Market Stability and Enrollment
By prioritizing a one-time check over sustained outreach and Navigator funding, the administration may be contributing to a "death spiral" in certain markets. Without robust outreach, younger and healthier individuals are less likely to enroll, leaving a sicker, more expensive pool of enrollees. This, in turn, drives premiums higher, far exceeding the $500 benefit provided by the refund.
2. Selective Populism
The choice to ignore the 95% of enrollees who are subsidized suggests a policy shift toward favoring higher-income Marketplace participants. While subsidized enrollees are shielded from the full brunt of premium increases, they also contributed to the user fee revenue. By excluding them, the administration is effectively using a pool of money funded by all enrollees (and taxpayers) to benefit a specific 5%.
3. Fiscal Precedent
If the Trump administration successfully issues these checks without a legal challenge, it sets a precedent for the "politicization" of user fees. Future administrations might use surplus regulatory fees in other departments—such as the FDA or the SEC—to issue "refunds" to favored constituencies during election cycles, fundamentally changing how federal agencies are funded and audited.
4. The 2027 Outlook
Looking ahead to 2027, the situation for unsubsidized enrollees remains grim. CMS documents project that benchmark premiums will rise by another 11% on average. For a 40-year-old, this represents an additional $876 annually. Consequently, the $500 "refund" of 2026 will be entirely erased by the price hikes of 2027, leaving consumers in a worse net-financial position than they were during the Biden administration’s period of "over-collection."
In conclusion, while the $500 checks offer a moment of political theater and a small measure of relief for approximately one million people, they do little to address the systemic affordability crisis triggered by the expiration of enhanced subsidies. As premiums continue to climb into the five-figure range for older Americans, the "Working Families Obamacare Refund" may ultimately be remembered more for its novelty than its efficacy.

