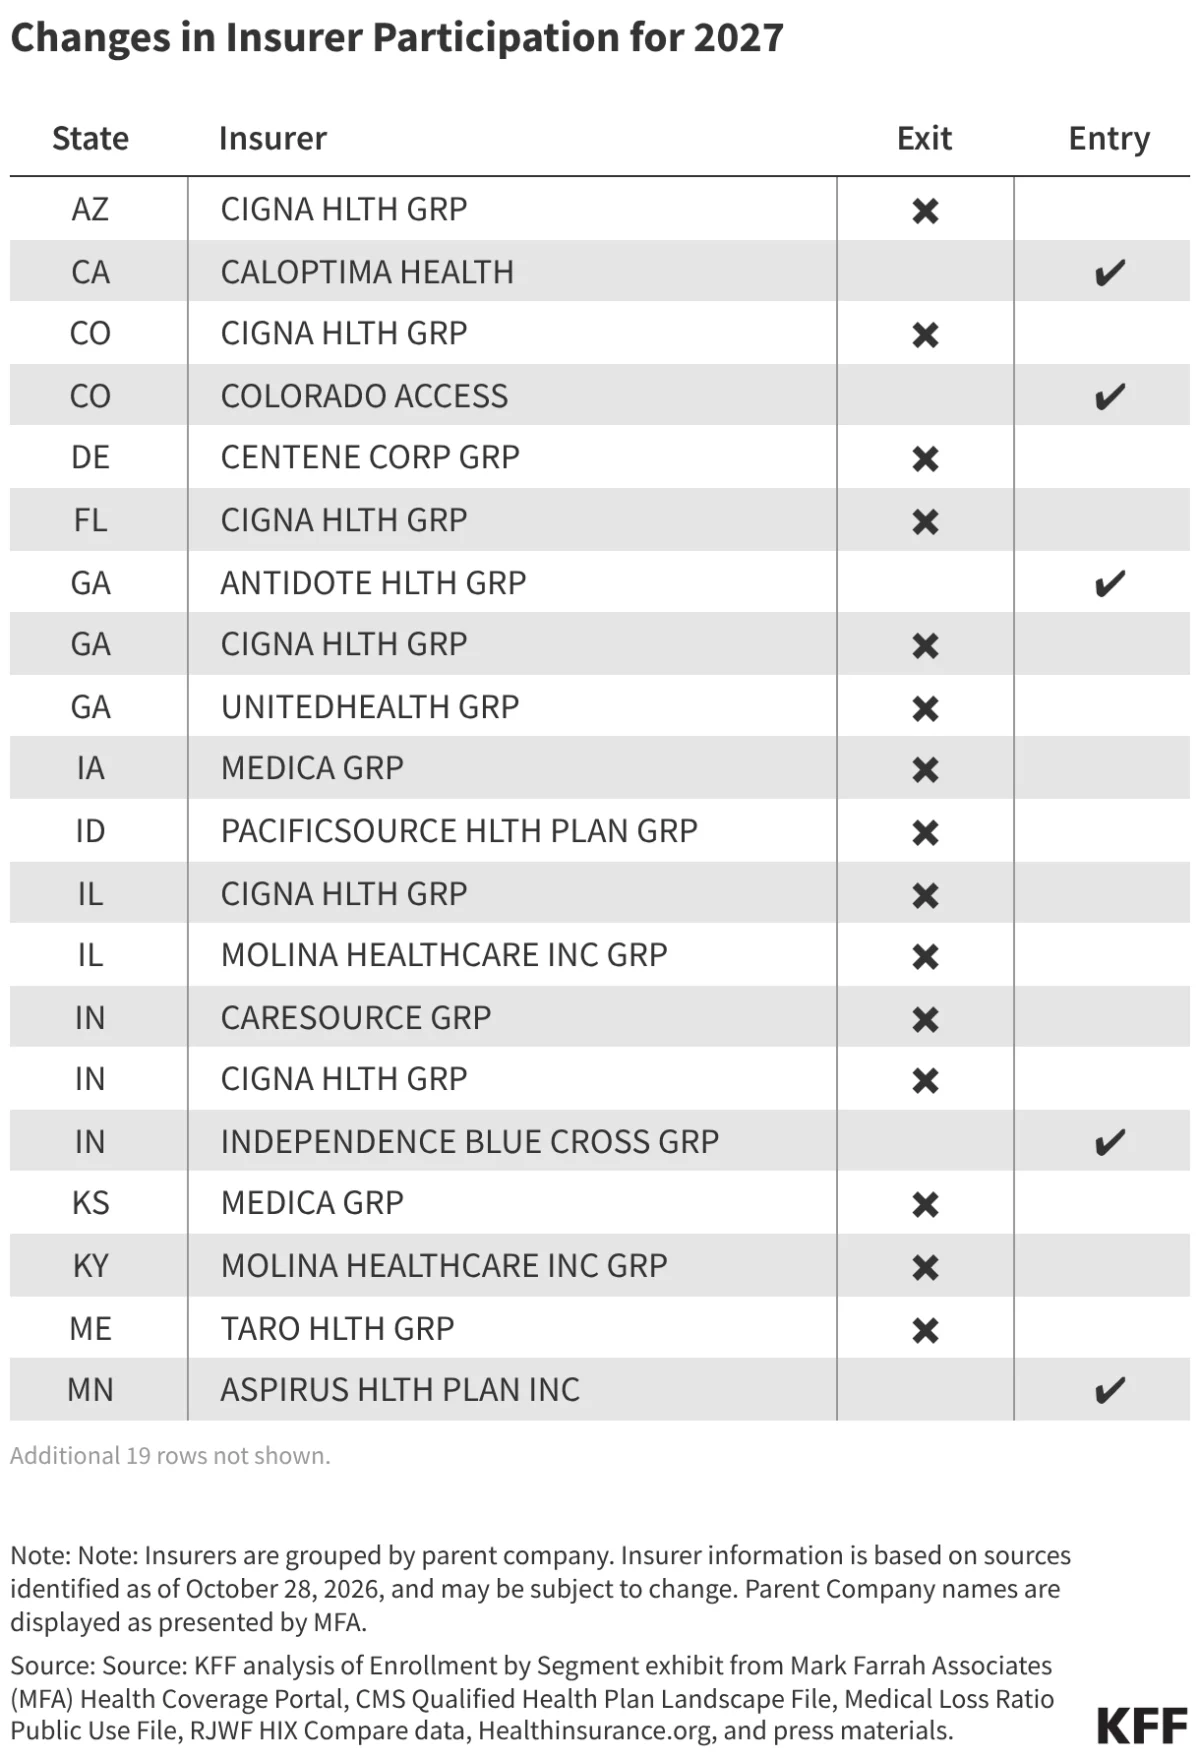
WASHINGTON D.C. — The landscape of the American health insurance market is undergoing its most significant structural shift since the implementation of the Affordable Care Act (ACA). As of late October 2026, a wave of carrier departures and strategic pivots has signaled the end of the "subsidy-fueled boom" that characterized the early 2020s. With the expiration of enhanced premium tax credits at the end of 2025, the 2027 plan year is shaping up to be a period of contraction, rising premiums, and diminished consumer choice.
n
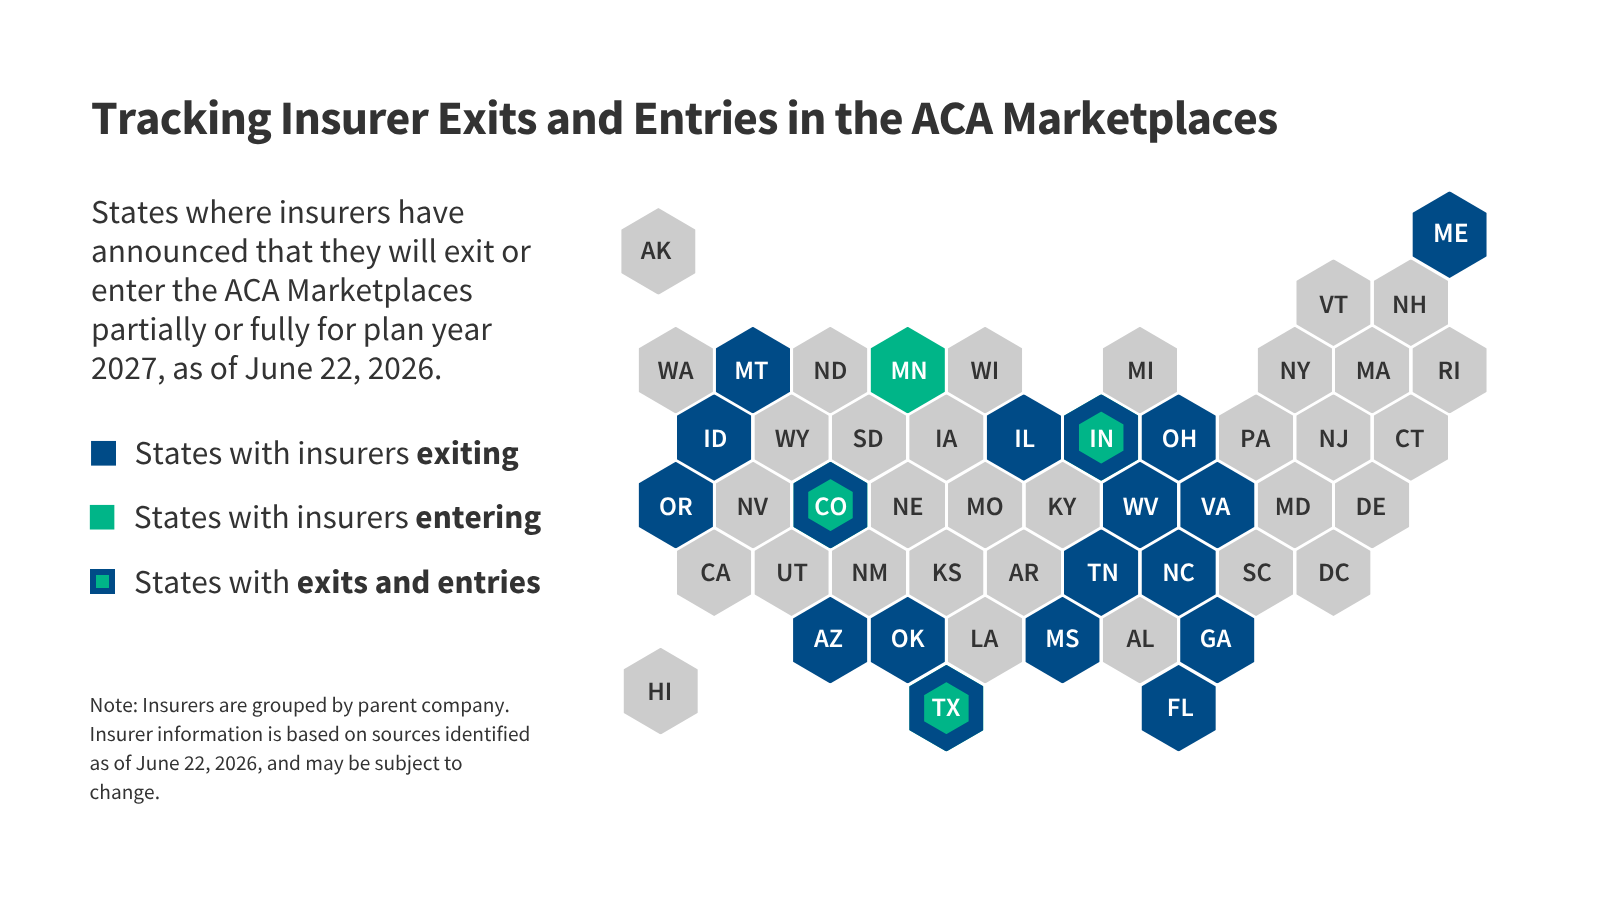
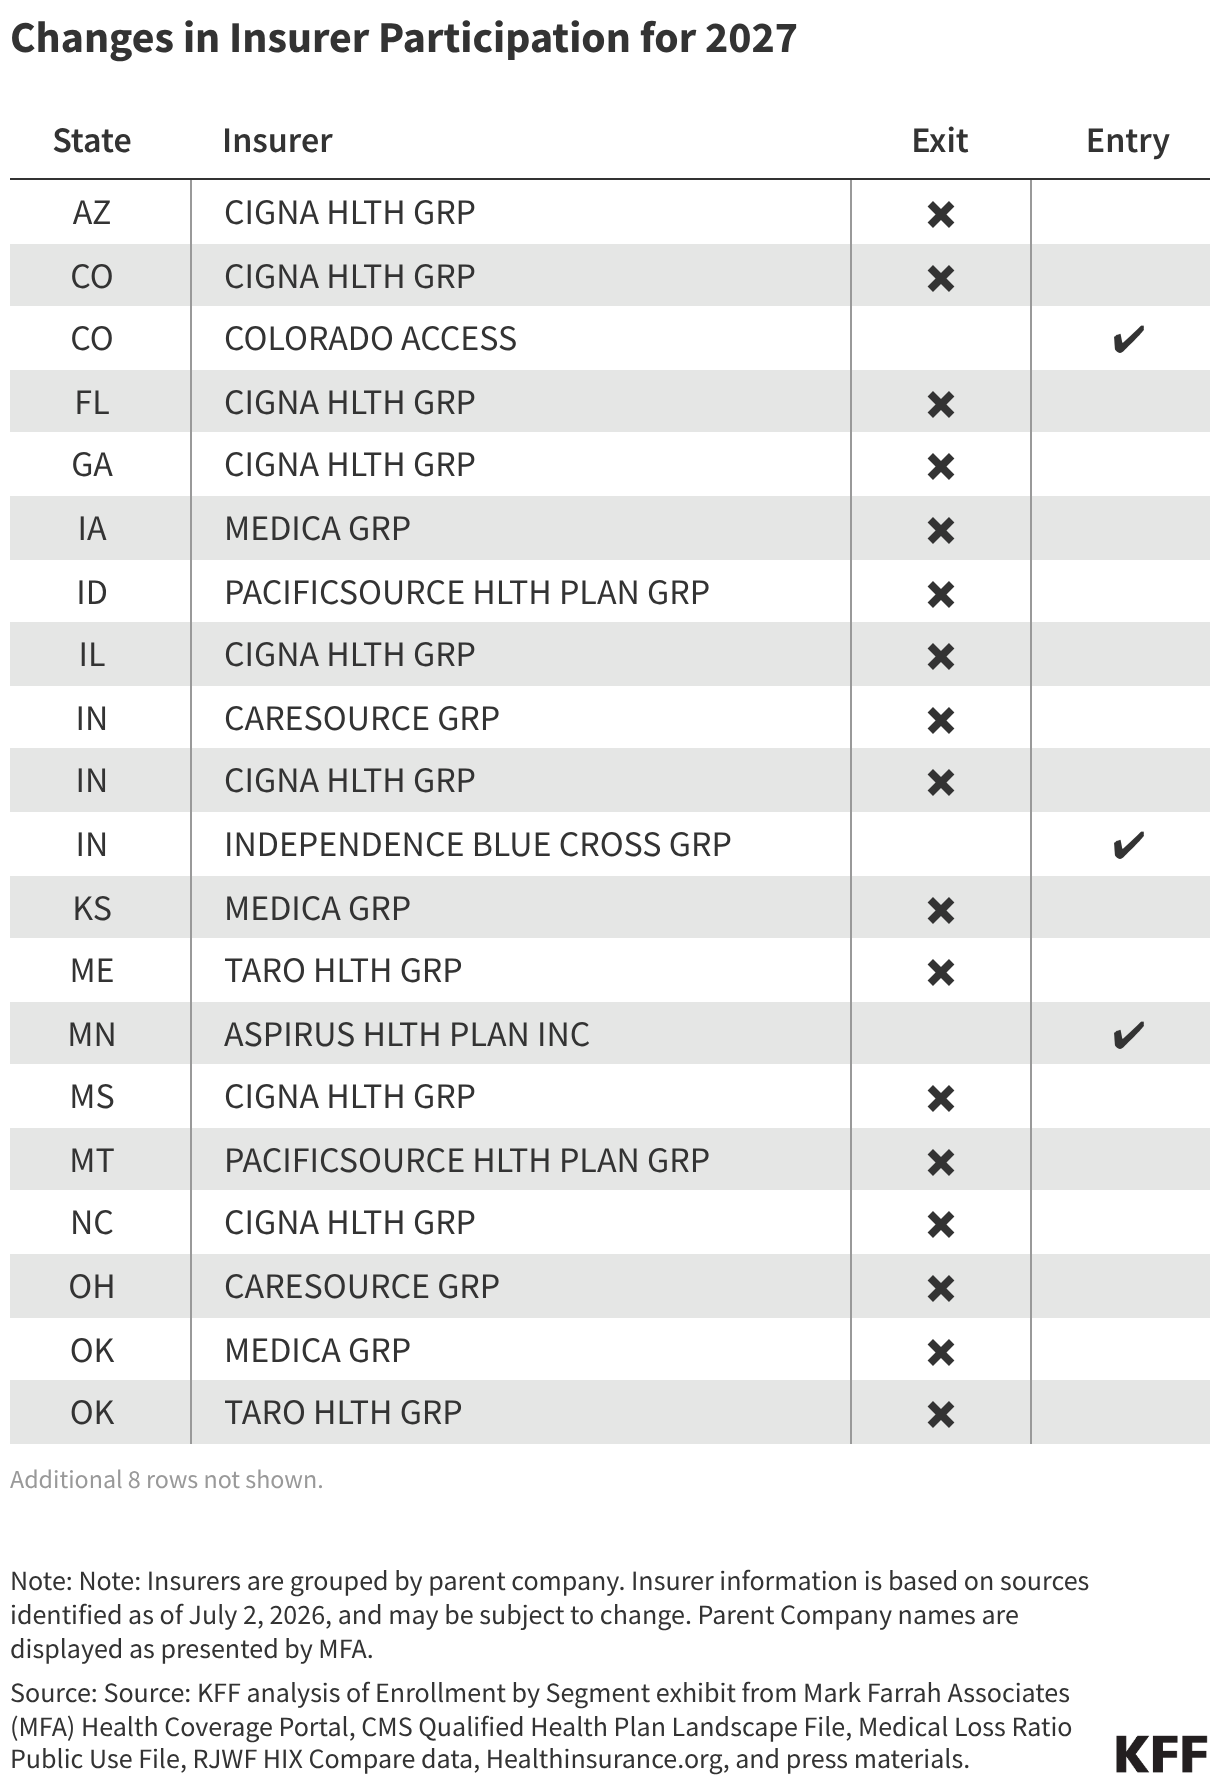
New data reveals that 11 major insurance carriers have announced their intention to exit the ACA Marketplaces in 2027, either partially or entirely. While seven carriers have announced plans to enter new markets, the net effect is one of consolidation and caution. This exodus follows a dramatic drop in enrollment—exceeding one million individuals between the 2025 and 2026 enrollment periods—leaving policymakers and healthcare advocates concerned about the long-term stability of the individual exchange.
n
n
Main Facts: A Market in Flux
n
The current volatility in the ACA Marketplaces is primarily driven by the removal of the financial "safety net" provided by the federal government during the post-pandemic era. The enhanced premium tax credits, which made coverage affordable for a broader swath of the middle class, were allowed to expire on December 31, 2025.
n
The fallout from this expiration has been swift:
n
- n
- Carrier Exits: 11 insurers are scaling back their footprint for 2027. This includes major national players like Cigna, which is exiting the individual market entirely across 11 states.
- Enrollment Decline: Official figures show a drop of over one million enrollees in the 2026 Open Enrollment Period compared to the previous year. Analysts expect further "churn" and membership attrition throughout the remainder of 2026.
- Strategic Realignment: Insurers are no longer viewing the ACA Marketplace as a high-growth sector. Instead, many are refocusing on employer-sponsored insurance and Medicare Advantage, where margins are perceived to be more stable.
- Limited New Entries: While seven carriers are entering new state markets, these are often targeted, niche expansions rather than broad national commitments, suggesting a "cherry-picking" approach to stable risk pools.
n
n
n
n
n
n
Chronology: From Expansion to Contraction (2021–2027)
n
To understand the current crisis, one must look at the artificial environment created by federal policy over the last five years.
n
The Expansion Era (2021–2025)
n
During the COVID-19 pandemic and the subsequent recovery, the American Rescue Plan Act (ARPA) and the Inflation Reduction Act (IRA) provided enhanced subsidies. These credits eliminated premiums for many low-income enrollees and capped premium costs at 8.5% of income for higher-earning households. This led to record-breaking enrollment, reaching over 21 million people by 2025. During this period, insurers flocked to the Marketplace, lured by a massive, government-subsidized customer base.
n
The Pivot Point (Late 2025)
n
As the expiration of these credits loomed, health policy experts warned of a "subsidy cliff." Despite legislative efforts to extend the credits, they were allowed to sunset at the end of 2025. This immediately increased the out-of-pocket costs for millions of Americans, particularly those in the "middle-income" bracket who no longer qualified for significant financial assistance.
n
The 2026 Open Enrollment Shock
n
The first tangible evidence of market decay appeared in early 2026. As premiums surged for unsubsidized enrollees, more than a million people dropped their coverage. Many transitioned to "skimpy" short-term plans or became uninsured, while others were priced out of the market entirely.
n
The October 2026 Announcements
n
By October 28, 2026, the data for the upcoming 2027 plan year became clear. Insurers, having analyzed their Q1 and Q2 2026 financial performances, realized that the shrinking pool of enrollees was becoming "sicker" on average—a classic sign of adverse selection. This prompted the current wave of 11 carrier exits.
n
n
Supporting Data: The Impact of Adverse Selection
n
The health of an insurance market depends on a balanced "risk pool"—a mix of healthy individuals who pay premiums but use few services, and sicker individuals who require expensive care. When subsidies expire, it is typically the healthy, price-sensitive individuals who drop coverage first.
n
The Cigna Case Study
n
Cigna’s departure serves as a bellwether for the industry. In its Q1 2026 earnings report, Cigna noted that its on-exchange enrollment stood at approximately 350,000 individuals. While this number seems substantial, the company determined that the individual market no longer aligned with its growth strategy. By exiting 11 states, Cigna is signaling that the administrative costs and risk volatility of the ACA no longer justify the investment.
n
Competition Metrics
n
In several states, the exit of multiple insurers will leave consumers with significantly fewer options. In 2025, the average consumer could choose from five or more insurers. For 2027, projections suggest that in many rural counties, consumers may be left with only one or two "monopoly" providers. Historically, a lack of competition in the ACA Marketplace has led to double-digit premium increases and narrower provider networks.
Enrollment Trajectory
The decline of one million enrollees is likely just the beginning. The Kaiser Family Foundation (KFF) has indicated that as the 2026 plan year progresses, more individuals are expected to drop off the rolls due to non-payment of premiums, as the true cost of unsubsidized insurance hits household budgets.
Official Responses: Corporate and Political Perspectives
The reaction to these market shifts has been divided along predictable corporate and ideological lines.
The Corporate View: Profitability Over Presence
Insurers have been blunt about their motivations. Cigna’s leadership articulated a sentiment shared by many departing carriers. Brian Evanko, a top executive at Cigna, described the individual market as a "small business" for the company that has been "shrinking in recent years." He stated that the decision to exit would allow the group to "further intensify focus on our core growth platforms." This suggests that for major diversified health giants, the ACA is increasingly seen as a liability rather than an opportunity.
The Regulatory View: Maintaining Stability
State insurance commissioners are working to manage the fallout. In states where multiple carriers are exiting, regulators are attempting to fast-track the entry of smaller, regional insurers to prevent "bare counties" (areas with no exchange insurers). However, these smaller entities often lack the negotiating power with hospitals that national carriers possess, potentially leading to higher costs for consumers.
The Political View: A Midterm Flashpoint
As the 2026 Midterm Elections approach, healthcare has returned to the forefront of the national debate. Democrats have pointed to the carrier exits as evidence that the enhanced subsidies must be reinstated to stabilize the market. Republicans, conversely, argue that the exits prove the ACA’s fundamental instability and are calling for alternative market-based reforms that move away from the exchange model.
Implications: What This Means for 2027 and Beyond
The retrenchment of insurers from the ACA Marketplace carries profound implications for the American healthcare system and the millions who rely on it.
1. The "Death Spiral" Risk
The primary concern for 2027 is the risk of a "death spiral." As healthy people leave and insurers exit, the remaining pool of enrollees becomes more expensive to cover. This forces the remaining insurers to raise premiums even higher, which in turn drives out the next tier of healthiest enrollees. If not corrected by policy intervention, this cycle could render the individual market unsustainable in several states.
2. Decreased Consumer Choice and Access
For the consumer, fewer insurers mean fewer choices of doctors and hospitals. Remaining insurers are likely to implement "narrow networks" to control costs. This means a patient might find that their long-term specialist or preferred local hospital is no longer "in-network," forcing them to either pay out-of-pocket or switch providers.
3. The Burden on the "Unsubsidized"
The individuals most affected are those who earn just above the threshold for standard subsidies but were previously helped by the "enhanced" credits. These middle-class families are facing a "double whammy": they must pay the full, unsubsidized premium at a time when those premiums are rising due to market instability.
4. Pressure on the Safety Net
As people lose exchange coverage, there will be increased pressure on community health centers and emergency rooms. Those who become uninsured often delay preventative care, leading to more acute—and expensive—medical crises later on.
5. Future of the ACA
The 2027 plan year will be a litmus test for the ACA’s resilience. If the market can stabilize with a smaller, more concentrated group of insurers, the ACA may survive as a niche product. However, if the exits continue into 2028, it may force a total legislative overhaul of how individual health insurance is delivered in the United States.
Conclusion
The data from October 2026 serves as a stark warning. The ACA Marketplace is no longer the burgeoning sector it was two years ago. As 11 carriers prepare to depart and enrollment figures continue to trend downward, the 2027 plan year will be defined by a search for stability in an increasingly volatile environment. For millions of Americans, the result will be a more expensive, less competitive, and more complicated path to securing health insurance.

