WASHINGTON D.C. — As the Affordable Care Act (ACA) Marketplace prepares for the 2027 Open Enrollment period beginning November 1, 2026, the American healthcare landscape stands at a precarious crossroads. Following a year of seismic shifts—including the expiration of enhanced federal subsidies and the implementation of the landmark 2025 budget reconciliation law, colloquially known as the “One Big Beautiful Bill Act”—consumers are facing a dramatically different environment than in previous years.
n
With premiums climbing for the second consecutive year and federal eligibility requirements tightening, the 2027 enrollment cycle is expected to be defined by a shrinking market, increased state-level intervention, and a complex web of litigation that has left several key regulations in a state of suspended animation.
n
n
I. Main Facts: The 2027 Landscape at a Glance
n
The 2027 Open Enrollment period is characterized by three dominant themes: affordability challenges for the middle class, a contraction of the individual market, and a significant shift in federal oversight.
n
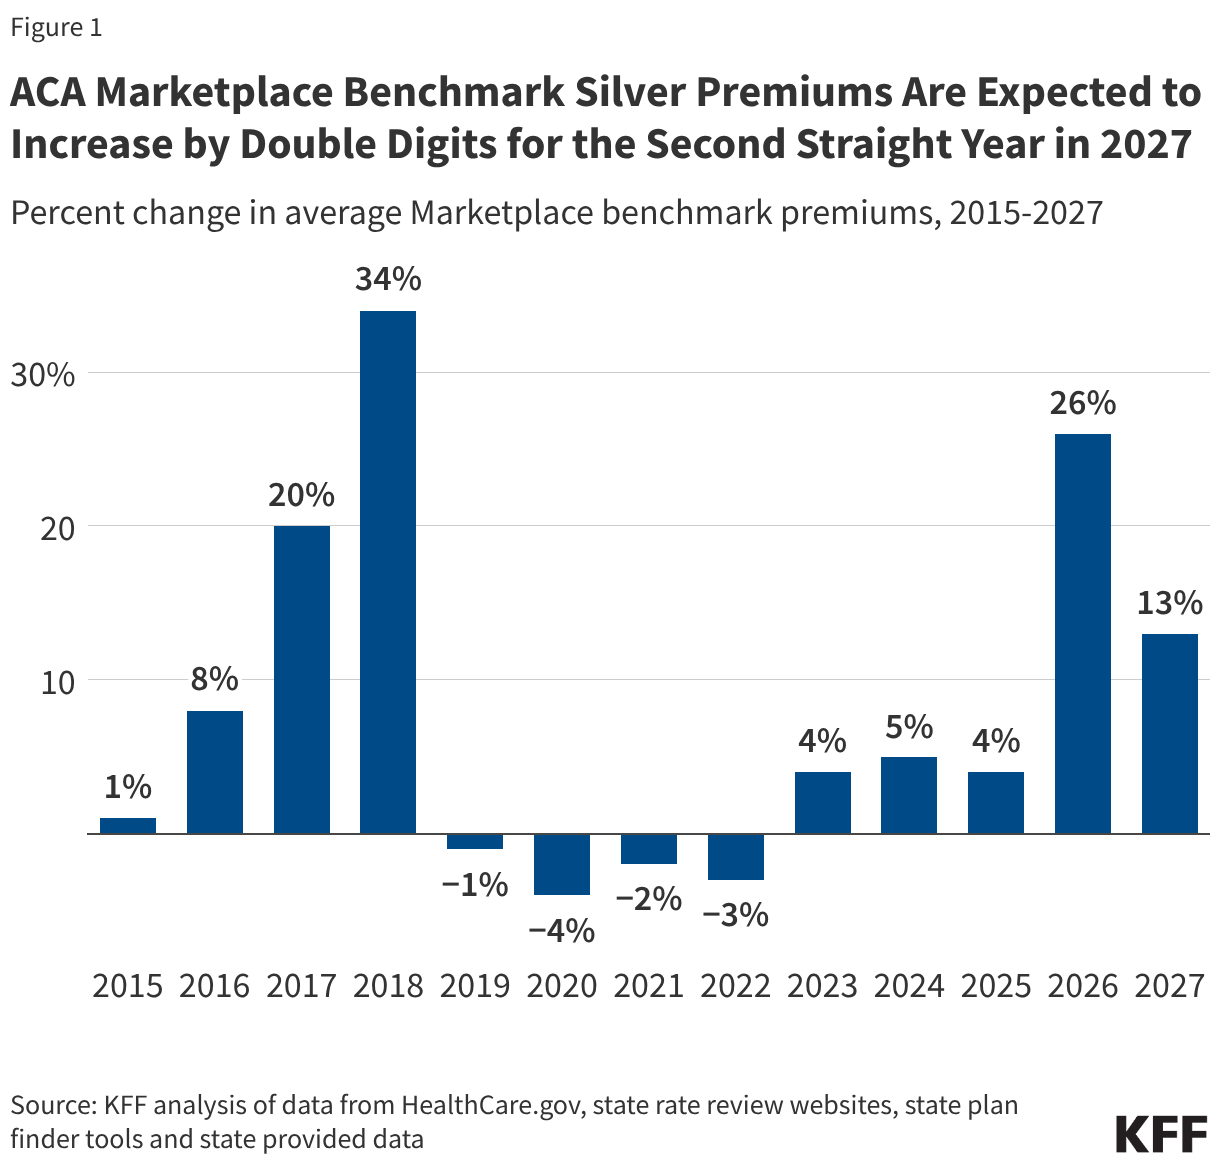
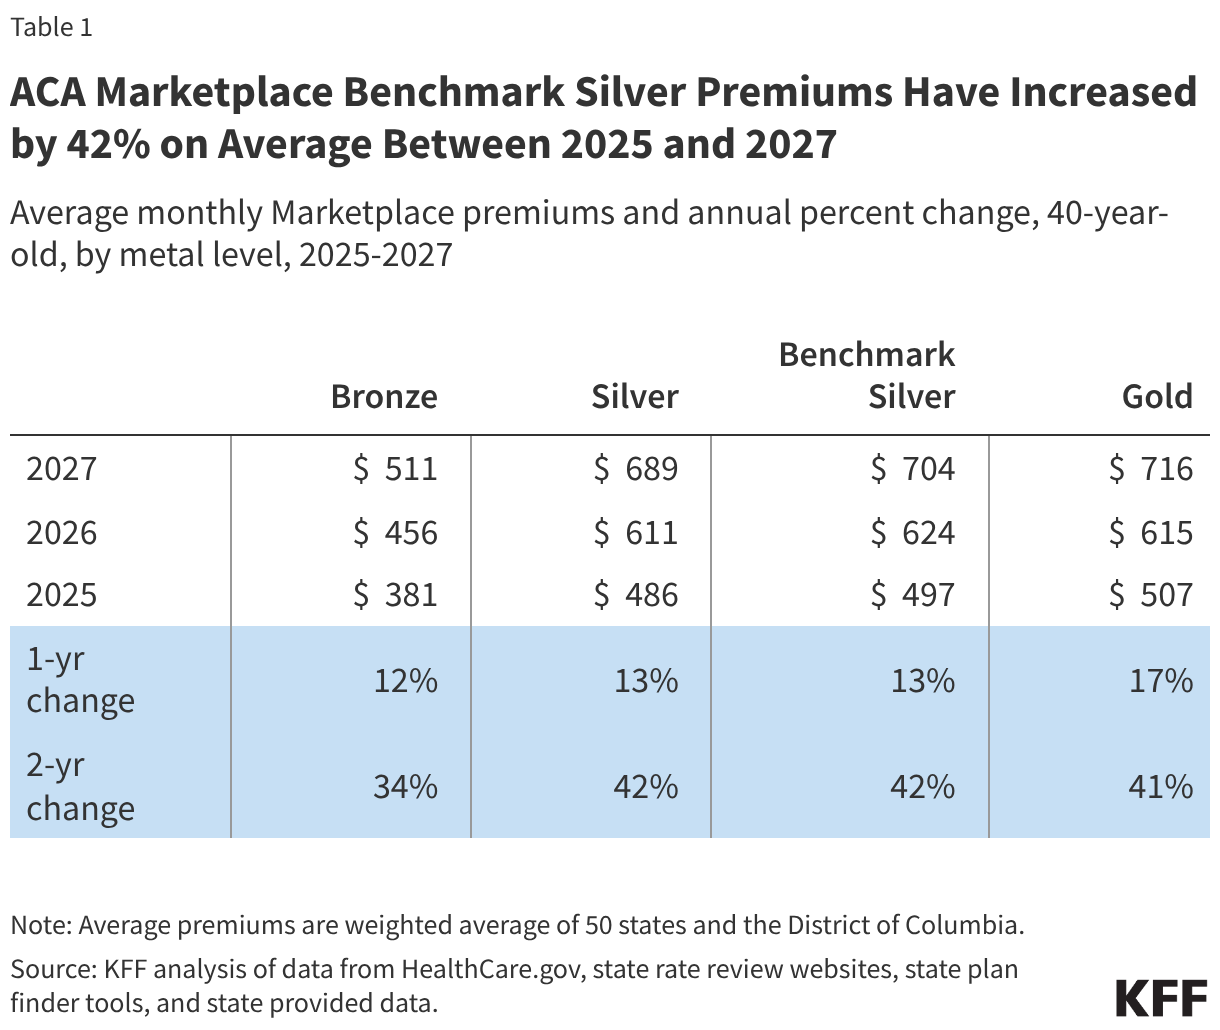
The Premium SurgenFor the second year in a row, ACA Marketplace enrollees will see double-digit increases in their monthly costs. While insurers initially proposed a median increase of 15%, finalized benchmark silver premiums have settled at an average increase of 13%. This follows a staggering 26% rise between 2025 and 2026, resulting in a cumulative premium hike of 42% over a two-year period.
n
Enrollment ContractionnThe "enrollment boom" of the early 2020s has officially ended. Following the expiration of the enhanced premium tax credits (PTCs), the Congressional Budget Office (CBO) projects that Marketplace enrollment will plummet from a 2025 peak of 22.4 million to just 13.1 million by the end of 2027.
n
Legislative and Regulatory ReversalnThe Trump administration’s 2025 budget reconciliation law has begun to dismantle several Biden-era expansions. Key changes include the elimination of repayment limits for excess tax credits, the introduction of Medicaid work requirements as a prerequisite for Marketplace subsidies, and the narrowing of eligibility for lawfully present immigrants.
n
n
II. Chronology: The Road to the 2027 Cycle
n
To understand the volatility of the 2027 enrollment period, one must look at the sequence of policy shifts that occurred over the preceding 24 months.
n
- n
- January 2025: The "One Big Beautiful Bill Act" is signed into law, setting the stage for the expiration of enhanced subsidies and the introduction of new fiscal controls.
- November 2025: The 2026 Open Enrollment begins, marking the first period without enhanced premium tax credits. Enrollment falls by 1.2 million almost immediately.
- February 2026: HHS announces a 90% cut to the ACA Navigator program, significantly reducing the available "boots on the ground" for enrollment assistance.
- June 2026: Data reveals a massive exodus from the broader individual market, with total enrollment falling 18% (4.6 million people) in just six months.
- September 2026: CMS cancels 760,000 "phantom" enrollments identified as fraudulent. Simultaneously, HHS announces a temporary moratorium on the registration of new brokers.
- November 1, 2026: 2027 Open Enrollment officially opens. For the first time, residents in 43 states and D.C. must navigate the intersection of Medicaid work requirements and Marketplace eligibility.
n
n
n
n
n
n
n
n
III. Supporting Data: The Economics of the 2027 Marketplace
n
The 13% average premium increase for 2027 is not uniform across the country, and the underlying drivers suggest a deteriorating risk pool.
n
The Geography of Cost
n
States utilizing the federal Healthcare.gov platform are seeing a relatively moderate benchmark silver premium increase of 11%. In contrast, states that operate their own independent exchanges are facing a steeper 16% hike. This disparity is a reversal of the 2025–2026 trend, where federal-platform states bore the brunt of the initial subsidy expiration shock.
n
The "Risk Pool Tax"
n
In their rate filings, insurers have been transparent about why costs are rising. Beyond the general inflation of medical services—which is also affecting employer-sponsored plans—insurers estimate that the "deterioration of the risk pool" added approximately four percentage points to 2027 premiums. As subsidies vanish, healthier, younger individuals are the first to drop coverage, leaving a sicker, more expensive population in the pool, which necessitates higher premiums for everyone else.
n
The Subsidy Gap
While the majority of enrollees still receive some form of subsidy, the "subsidy cliff" has returned with a vengeance. Individuals earning more than 400% of the Federal Poverty Level (FPL) are now entirely ineligible for federal financial assistance. For a family of four in many states, this means paying the full, unsubsidized cost of a silver plan, which could easily exceed $2,000 per month.
IV. Official Responses: A Divided Regulatory Front
The response to the 2027 enrollment challenges has been split between federal efforts to tighten the belt and state efforts to shield residents.
Federal Oversight and Anti-Fraud Initiatives
HHS and CMS have pivoted toward "Marketplace Integrity." The cancellation of 760,000 enrollees in late 2026 was a response to widespread reports of "phantom" enrollments, where brokers allegedly signed up individuals without their consent to collect commissions.
"We are implementing new safeguards to protect consumers from predatory marketing," an HHS spokesperson stated regarding the 2027 Payment Parameters. "This includes prohibiting cash rebates for enrollment and requiring brokers to submit all marketing materials for federal audit." However, critics argue that the temporary moratorium on new brokers—estimated to prevent 19,000 agents from entering the market—will further limit access to help for legitimate enrollees.
The Insurer Exit
Private carriers are showing signs of retreat. Cigna, a major player in the individual market, announced its complete exit from the Marketplace in all 11 states where it previously operated. Insurers cite the "unpredictability of the risk pool" and the "expiration of federal cushions" as the primary reasons for their departure.
State-Funded Backfills
Recognizing the potential for a public health crisis, several states have stepped in where the federal government stepped back:
- New Mexico: The state has fully backfilled the lost federal subsidies with state funds, resulting in the only recorded enrollment growth in the nation during the 2026 cycle.
- California: Covered California has expanded state-funded subsidies to households earning up to 200% FPL to mitigate the loss of the enhanced federal credits.
- Rhode Island and Virginia: Both states have launched new, state-specific subsidy programs for the 2027 plan year to prevent a mass exodus of enrollees.
V. Implications: The "Uninsured Gap" and Legal Limbo
The 2027 enrollment period carries profound implications for the long-term viability of the ACA and the financial security of millions of Americans.
The Medicaid-Marketplace Trap
One of the most complex changes in 2027 is the link between Medicaid work requirements and Marketplace tax credits. In the 43 states now required to implement these requirements, an individual who is disenrolled from Medicaid for failing to meet work or reporting rules is now statutorily barred from receiving Marketplace subsidies. This creates a "dead zone" where a low-income individual could be ineligible for both Medicaid and subsidized private insurance, leaving them with no affordable path to coverage.
The Immigrant Impact
The 2025 reconciliation law’s narrowing of tax credit eligibility for lawfully present immigrants (excluding refugees and asylees from subsidies) is projected to increase the number of uninsured Americans by one million by 2035. While these individuals can still purchase plans, the "sticker shock" of unsubsidized premiums is expected to drive most out of the market.
The Uncapped Repayment Risk
Enrollees in 2027 face a new tax-season peril. The 2025 law eliminated the caps on how much an individual must repay if their year-end income exceeds their initial estimate. In previous years, these repayments were capped to prevent financial ruin; starting in the 2026 tax year (filed in early 2027), enrollees may be liable for the entire difference. This change makes accurate income projection more critical—and more stressful—than ever before.
The Shadow of Litigation
Finally, the 2027 cycle begins under a cloud of legal uncertainty. Four major cases—Columbus I & II and California I & II—are currently challenging the federal government’s authority to implement these integrity rules and payment parameters. With several provisions currently stayed by court order, enrollees and brokers are operating in a regulatory environment that could change mid-enrollment depending on a judge’s ruling.
Conclusion
The 2027 ACA Open Enrollment is more than just an annual sign-up period; it is a stress test for the American healthcare safety net. As premiums rise and federal support narrows, the burden of maintaining coverage has shifted heavily onto the states and the individuals themselves. For those navigating the Marketplace this November, the message is clear: the era of easy expansion is over, and the era of the "informed consumer" has begun.

